Developer Funding Leads Cyprus — How to Qualify Capital Contacts Before Due Diligence
Learn how Cyprus developers can prepare a project, qualify funding contacts and choose between bank debt, equity or a joint venture.
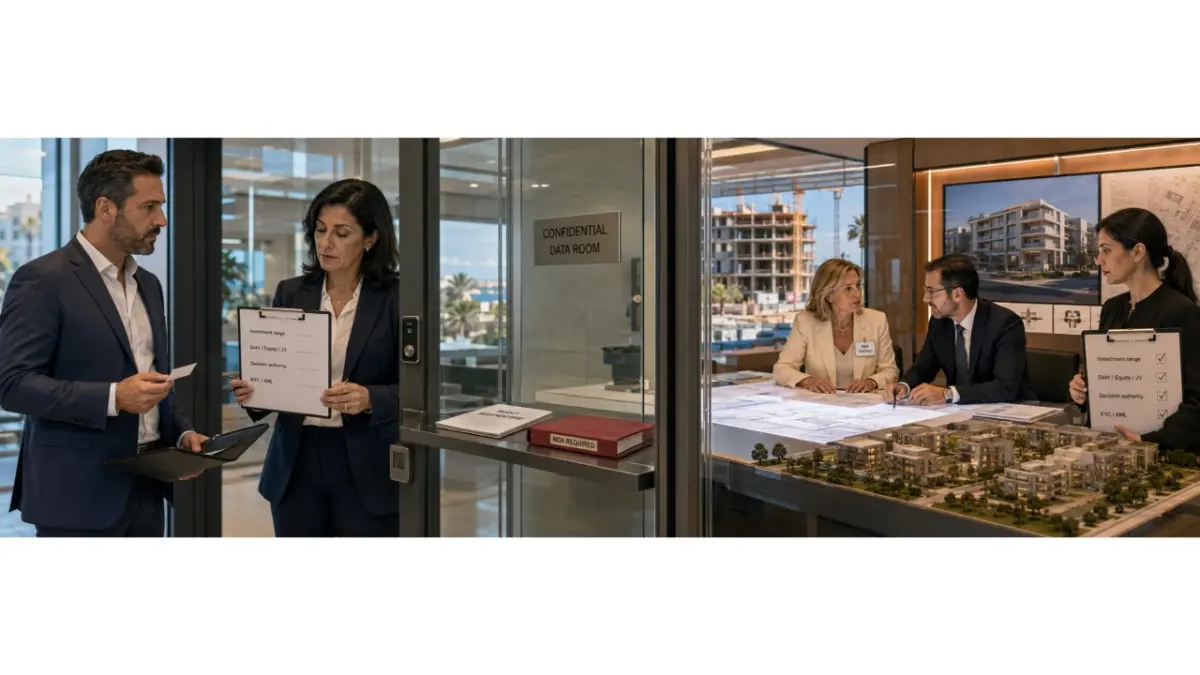
A developer preparing a residential project receives an introduction to someone described as an investor. The contact asks for the full financial model, land documents and projected returns but gives no clear information about investment size, preferred deal structure or decision-making authority. Sending the complete package would expose sensitive information before the developer knows whether the opportunity is relevant. Finding developer funding leads cyprus is therefore a matter of preparing the project, identifying suitable capital providers and qualifying each contact before sharing confidential materials.
A Contact Is Not Yet a Funding Lead
A funding lead is a potential source of capital whose requirements may fit the project. The contact could represent a bank, family office, private lender, investment company or prospective joint-venture partner. An expression of interest alone does not establish available capital or a workable deal.
Before progressing, the developer needs to understand the party’s investment range, relevant experience, time horizon and decision-making authority. The preferred structure matters too: a lender seeking secured repayment has different requirements from an equity partner seeking a share of the project and a role in its decisions.
Treating every introduction as a qualified opportunity consumes management time and can expose confidential information. Useful investor connections depend on a clear match between the project and the capital provider.
Matching the Funding Model to the Project
The appropriate funding model depends on the development stage and what the money must cover. Land acquisition, planning, construction and refinancing present different risks and cash-flow needs.
The main options include:
- Bank or other debt financing: borrowed capital with agreed repayment terms, often subject to security and lender assessment.
- Private debt: lending terms negotiated with a private capital provider, requiring careful review of costs, security and repayment obligations.
- Equity investment: capital provided in exchange for an ownership or profit interest and agreed decision rights.
- Joint venture: a structure in which parties combine capital, land, development work or other contributions under negotiated terms.
Developers should compare total cost, security, control, repayment pressure and the effect of delays. A loan with a lower stated rate may still be unsuitable if repayment falls due before the project can generate the required cash.
Preparing the Project Before Contacting Investors
Outreach begins with a project that can be explained clearly. A potential capital provider needs enough information to assess whether the opportunity fits its mandate. The developer does not need to release the complete data room at first contact.
A short Project Investment Brief can present:
- The project location, proposed use and development stage.
- The developer’s position regarding the land and planning process.
- The proposed unit mix and broad project timetable.
- The amount sought and the intended use of funds.
- The type of funding or partnership being considered.
- The main project assumptions and risks, clearly distinguished from approved facts.
A suitable next step is:
Request the confidential project pack after qualification and NDA.
Detailed budgets, contracts, personal data, full projections and sensitive land documents belong in a controlled review process. The developer should decide what to share and when with its legal and financial advisers.
This preparation matters to financing new projects because it reveals gaps early. Unclear land rights, incomplete approvals, unsupported costs or an undefined route to repayment or exit can prevent a discussion from reaching due diligence.
Finding and Qualifying Relevant Contacts
Potential contacts may come through banks, professional advisers, existing partners, industry events, family offices, business networks and trusted introductions. A focused introduction can be more useful than broad promotion when it matches the project stage, funding range and preferred structure.
The first conversation should establish:
- What investment range is under consideration?
- Is the preferred structure debt, equity or a joint venture?
- Which locations and asset classes fit the party’s mandate?
- Which development stages will it consider?
- What risk profile and time horizon does it accept?
- Who makes the final decision?
- What relevant transaction experience does it have?
- Is it prepared for the identification and due-diligence checks required for the transaction?
- What information does it need before considering confidentiality terms and a formal review?
A contact unable to answer these questions can remain at an early pipeline stage. Enthusiasm, a request for documents or an introduction from a trusted person is not proof of available funding.
The same distinction applies to contacts found through agents and digital platforms. Visibility may start a conversation; it does not verify the other party’s capacity or authority.
A Practical Funding Pipeline
Consider a hypothetical Cyprus developer preparing a residential project. The land position and initial concept are established, but the developer needs either a joint-venture partner or private debt before progressing.
The team prepares a brief and approaches banks, family offices and relevant contacts introduced by professional partners. The message to each group reflects the funding model it may consider, rather than sending one generic request to every contact.
The CRM pipeline is organised as:
Identified → Contacted → Qualified → NDA → Materials Shared → Due Diligence → Terms Discussed → Rejected or Closed
One family-office contact is interested only in completed, income-producing assets. The team closes that opportunity before sharing sensitive documents. Another contact confirms an interest in residential joint ventures at the relevant stage, identifies an investment range and names the decision-maker. The team can then discuss confidentiality terms and the next level of review.
Qualification does not guarantee funding. It helps the developer distinguish productive discussions from activity that is unlikely to advance.
Useful indicators include qualified contacts, responses, confidentiality agreements, due-diligence reviews and term discussions. None should be counted as capital raised before the funding transaction is completed.
Cyprus Safeguards and the Role of MLS RealtyHub
Funding arrangements may require checks relating to identity, beneficial ownership, source of funds and sanctions. The way an opportunity is structured or promoted may also bring investment-services, securities or crowdfunding rules into consideration.
Presenting a development project is different from offering an investment product or arranging finance. Developers should have qualified legal and financial professionals review the proposed structure and communications before distributing investment terms or accepting funds.
MLS RealtyHub can support project presentation and information management without acting as a lender or investment intermediary. Structured project data helps developers keep approved information consistent, while access controls can separate public project details from materials intended for authorised participants.
Developer CRM Integration can support contact records and pipeline stages. Developer API Integration can help align project information across connected systems, and Developer Dashboard can provide a view of project status. Their usefulness depends on the developer’s workflow and configuration.
These tools do not verify a potential investor, arrange financing or guarantee capital. Developer funding leads cyprus still require project preparation, qualification and professional review.
Frequently asked questions
What Is a Funding Lead in Real Estate?
It is a potential lender or financial partner whose requirements may fit a project. The lead becomes qualified when the developer has established its funding range, preferred structure, relevant experience and decision-making authority.
How Do Developers Find Investors in Cyprus?
Contacts may come through banks, advisers, family offices, existing partners, business networks and trusted introductions. Each contact still needs to be assessed against the project’s stage and funding requirements.
What Documents Do Investors Want First?
A concise project brief can introduce the location, stage, land and planning position, proposed development and funding need. Detailed financial and legal records can follow through a controlled due-diligence process.